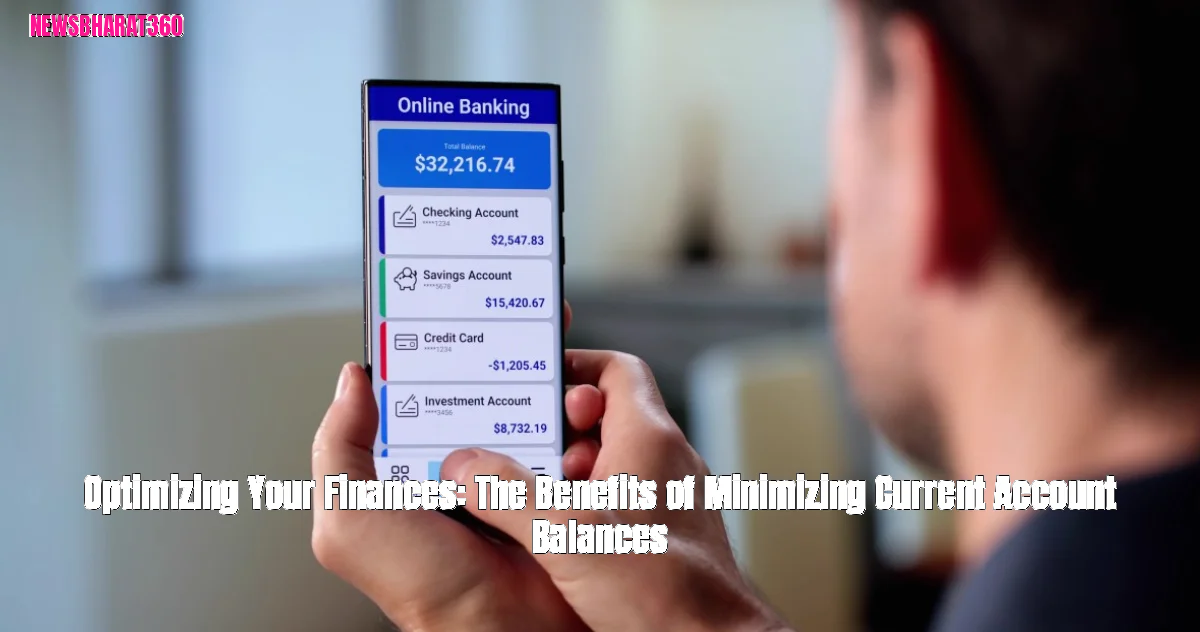

Maintaining a sizable balance in one's bank account can provide a sense of financial security, particularly when multiple bills are due and a timely payment is crucial. Nevertheless, having a substantial amount of money readily available does not necessarily indicate effective financial management. In reality, it may be an opportunity to earn additional income with minimal effort.
Not all bank accounts serve the same purpose, and understanding their functions is crucial for effective financial management. A current account is designed to facilitate daily transactions, such as receiving deposits, paying bills, and covering living expenses. However, keeping all savings in a current account may not be the most financially advantageous decision, as many traditional banks typically offer very low interest rates on these accounts.
Current accounts often come with relatively low interest rates, typically around 0.01% per annum. As a result, individuals with a $10,000 balance in such an account can expect to earn approximately $1 in interest over the course of a year, assuming the interest rate remains unchanged.
Rising prices for goods and services are causing the purchasing power of money to erode, as inflation gradually diminishes the value of one's currency.
Consider allocating only the funds necessary to cover your regular expenses, then transferring any excess to a high-yield savings account for optimal savings growth.
A recent study by Motley Fool Money found that approximately one-third of American households maintain their savings in accounts offering competitive interest rates. This discovery highlights a significant financial opportunity that remains largely untapped, as many households fail to capitalize on the potential for their savings to earn returns rather than remaining stagnant in traditional checking accounts.
The distinction between high-performance savings accounts and other banking products can be substantial. Presently, these accounts typically yield annual interest rates ranging from 3% to 4%, with actual returns subject to variation based on the specific bank and prevailing market conditions.
Individuals with a $20,000 savings account earning a 4% annual percentage yield can potentially earn approximately $800 in interest over a 12-month period, provided the interest rate remains constant and no withdrawals are made.
A savings account with a 0.01% yield would yield only $2 annually, whereas a current account designed to generate returns would produce significantly more. In fact, the difference could be substantial, resulting in a loss of approximately $798 per year if savings are kept in an account not intended for returns.
High-performance savings accounts frequently enable electronic transfers, allowing for quick access to funds when needed. This feature makes them a viable alternative to maintaining an emergency fund, while still preserving liquidity.
Consumer behavior is a significant factor to consider when evaluating the desirability of accumulating large amounts in the current account.
Users who discover a substantial balance in their bank accounts through mobile banking apps may experience a false sense of financial flexibility, potentially leading to impulsive decisions regarding discretionary spending, such as dining out or making unplanned online purchases.
Maintaining a current account with only the funds necessary to cover outstanding commitments enables individuals to establish more defined financial boundaries.
Separating savings in a separate banking institution can be an effective strategy to curb impulsive spending. By doing so, individuals can maintain control over their funds while minimizing the temptation to make unnecessary purchases, as the money remains accessible for transfer when needed but is no longer visible in their primary account.
Individuals should allocate a sum equivalent to one month's living expenses, encompassing essential costs such as rent, utilities, credit card payments, and other recurring obligations. The remaining funds can be divided between high-yield savings accounts and other investment vehicles, tailored to specific financial goals and requirements. It is essential to maintain a separate and readily accessible emergency fund to cover unexpected expenses, distinct from the allocated funds for daily living expenses.
When selecting a bank, it is crucial to examine the specific terms and conditions, including minimum balance requirements, potential fees, and interest rates. Some financial institutions offer combined checking and savings accounts, but the interest rates may vary between the two products.
Additional Stories of Interest