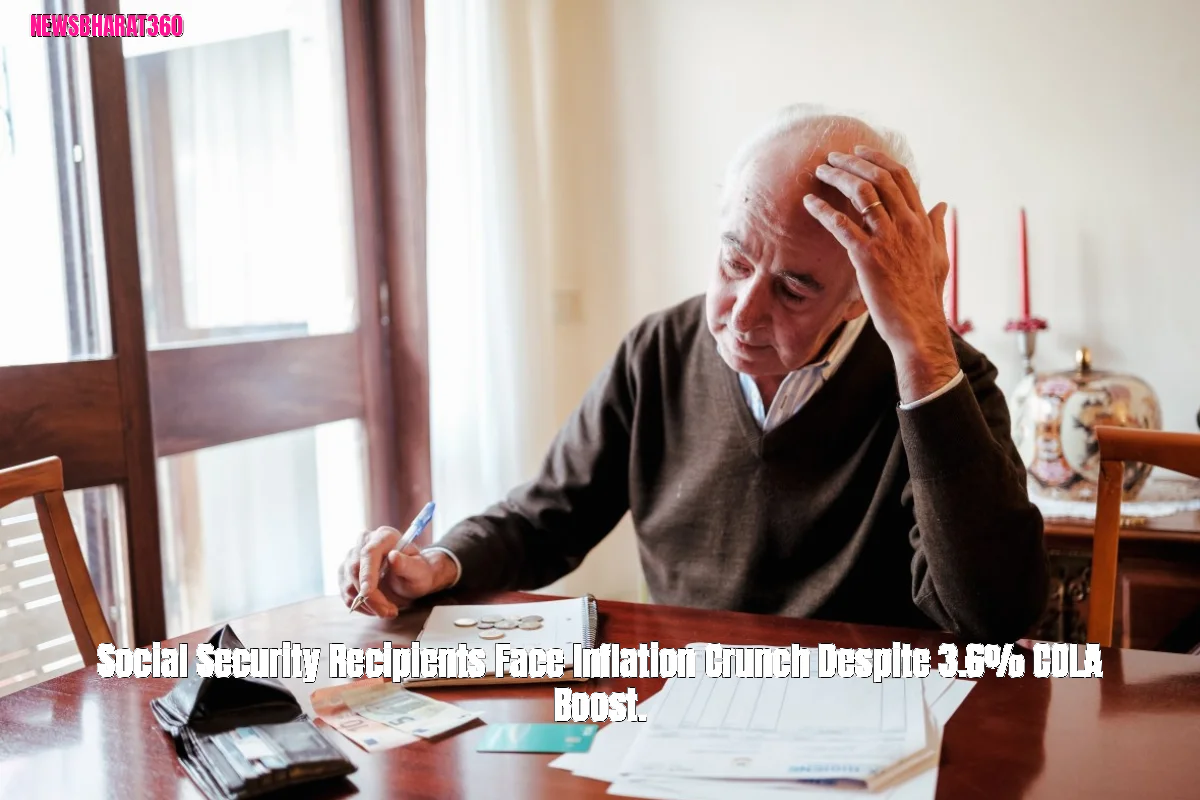

For many retirees, receiving a larger Social Security check each month is a welcome development, as it helps cover essential expenses such as rent, food, and bills. Nevertheless, the benefits of a higher payment may be short-lived, as rising daily living costs can quickly erode the additional funds.
The Social Security cost of living adjustment (COLA) for 2027 has been set at 3.6%, effective October 14. While this increase surpasses the 2.8% COLA for 2026, some beneficiaries may still feel that the boost is insufficient due to various factors.
AARP, a non-profit organization advocating for the rights of individuals over 50, reports that the average monthly profit is projected to increase from $2,087.52 to $2,162.67. This represents a monthly gain of $75.15, or an annual increase of $901.81.
The increased amount will not directly benefit retirees who rely on Medicare, as the Part B premium is typically deducted from their Social Security benefits.
Medicare recipients will receive a cost-of-living adjustment, or COLA, which aims to offset rising prices, although those with Medicare will experience a decrease in their COLA due to the deduction of Part B premiums from their benefit checks.
Estimates suggest that the average retiree may face a net increase of around $64 to $68 in their monthly expenses, following a projected $6.60 rise in Medicare Part B premiums.
The projected standard premium for 2027 is expected to be $209.50 per month, marking a slight increase from the $202.90 monthly premium in 2026.
Experts have identified an issue with the formula used to determine the adjustment, as the Cost of Living Adjustment (COLA) is currently based on an urban price index that may not accurately reflect the expenses of retirees, who tend to allocate a larger portion of their income towards healthcare costs.
Retirees and individuals with fixed incomes may experience higher cost-of-living increases than the overall inflation rate suggests, particularly in areas such as medical expenses, insurance premiums, and prescription medications. This disparity can occur even if their overall income rises, as personal expenses may grow at a faster rate than the general inflation index.
Medicare premium accounting practices were also raised as a point of concern by Boshardy.
Medicare premiums are not accurately represented in the calculation process, as they are predetermined annually by law rather than being directly measured in pharmacies.
Pivoters founder and CEO Scott Siff notes that expenses are likely to increase before the implementation of the upcoming adjustment.
Beneficiaries have been required to cover the increased costs for nearly 18 months prior to receiving the adjustment to their benefits.
The upcoming January price increase will be the latest in a series of higher costs that many consumers have already been facing for several months.
A recent survey conducted by AARP discovered that nearly 70% of adults aged 50 and above believe a cost-of-living adjustment of 5-8% would enable Social Security beneficiaries to more effectively manage their daily expenses. Conversely, only 23% of respondents deemed a 3.5% increase sufficient to meet their needs.
According to Myechia Minter-Jordan, executive director of AARP, nearly 20% of individuals lack retirement savings, and a greater number of people are experiencing financial insecurity this year compared to the previous year.
Concerns have been raised about the long-term viability of the program, with its managers projecting that the trust fund supporting its benefits may be depleted by 2032. If no corrective measures are implemented, the available income is expected to fall short of covering all anticipated benefits, necessitating a potential reduction of approximately 22% in payments.
Financial experts advise individuals to reassess their monthly budgets and explore alternative sources of income to support their retirement. Options to consider include employer-sponsored savings plans such as 401(k) and 403(b), individual retirement accounts (IRAs), personal savings, and pension plans.
Individuals nearing retirement should consider supplementing their Social Security benefits with alternative income sources. Reviewing employer-offered savings plans and contributing as much as possible within budget can help ensure a more comprehensive financial foundation in retirement.
Individuals may consider part-time or seasonal employment as an alternative, provided their personal circumstances permit. Prior to taking on additional work, it is recommended to verify whether the increased income could impact benefits for those who have not yet reached full retirement age.
Medicare beneficiaries are advised to take advantage of the open enrollment period, spanning from October 15 to December 7, to thoroughly evaluate and compare available options. This includes carefully examining the premiums, deductibles, and out-of-pocket expenses associated with each plan to make an informed decision.
The Cost of Living Adjustment (COLA) may provide some relief, but it does not ensure that the increased income will be sufficient to cover all rising expenses. Prior to allocating the additional funds, it is prudent to determine the net amount available after deductions and estimate the costs of essential needs for the upcoming year.
Individuals may find additional relevant information in related stories.