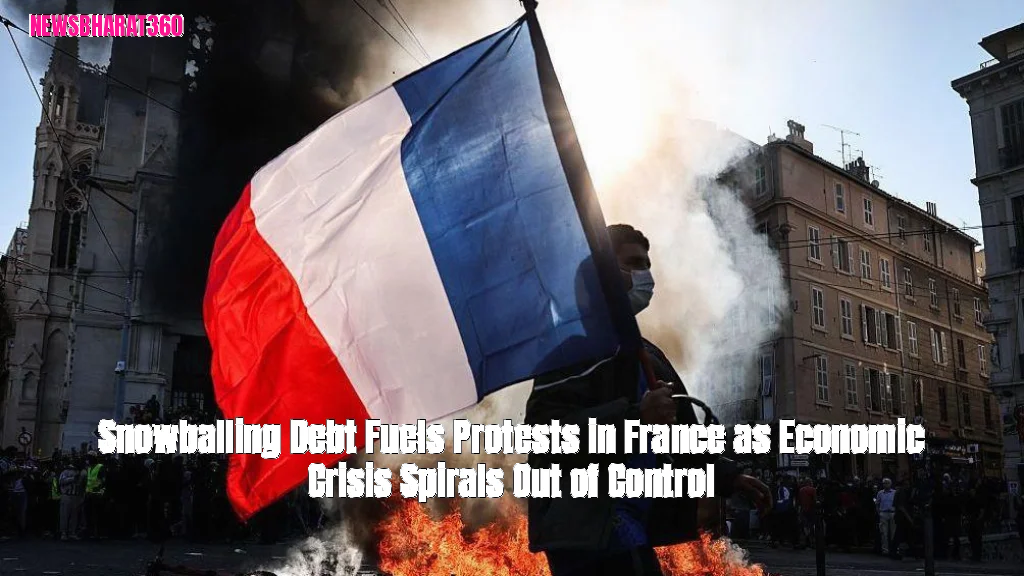

Protests and demonstrations have swept across France, with widespread public discontent evident in the country's streets.
A student-led protest initially sparked by concerns over deteriorating conditions in public schools has evolved into a broader movement encompassing issues such as the rising cost of living, limited opportunities for young people, and inadequate pension benefits.
France's capital city and other major metropolitan areas have been gripped by widespread looting and vandalism since last weekend, prompting the implementation of citywide shutdowns to restore order and quell the unrest.
A potentially more devastating crisis may be brewing in the financial markets, as a growing lack of confidence in French government bonds has become increasingly evident in recent weeks.
France, like numerous other nations, utilizes debt bonds to fund its present-day expenditures, providing investors with potential returns in the form of future profits in exchange for their investment.
Since the start of September 2026, France's risk premium has seen a significant surge, indicating escalating concerns over the long-term viability of its debt. This premium, which represents the additional cost France must pay investors to secure financing on debt markets compared to Germany, currently considered the euro area's most financially stable country.
Market concerns are rising over the French Republic's ability to meet its debt obligations, potentially leading to a default or suspension of payments, a scenario similar to Argentina's experience in 2001.
The French government currently maintains its ability to fund its operations.
French Finance Minister Roland Lescure recently stated to the BBC that bond demand remains strong, allowing the government to issue debt on a regular basis without encountering any difficulties, with new issues occurring every two weeks. The Governor of the Bank of France, Emmanuel Moulin, also noted that the country is not currently reliant on assistance from the European Central Bank.
The Ministry of Economy and Finance has acknowledged a decrease in the sale of long-term bonds, exceeding 30 years, attributed to diminished investor interest.
Economist Paul Krugman, a Nobel Prize laureate, has observed that financial markets are now viewing France as the latest economic concern in the Western world.
The French government, led by President Macron, acknowledges the need to address the public deficit and financial mismanagement. Despite efforts to implement budgetary reforms, the administration has faced opposition from a Parliament in which it holds a minority, as well as from protesters advocating for enhanced public services and opposing reductions to the French social welfare system.
French President Emmanuel Macron is currently grappling with multiple challenges as he attempts to reestablish stability on the streets and rebuild market confidence. Additionally, Macron is confronting another significant obstacle: the escalating cost of debt, which may further limit his ability to implement effective policy measures.
French Minister Lescure addressed the National Assembly on Monday, stating that the country is not being overwhelmed by a rapidly escalating debt burden, as evidenced by the international attention drawn by images of historic buildings engulfed in flames.
The term in question is a concept employed within the field of macroeconomics.
A country's debt burden is typically evaluated relative to its economic output, as measured by Gross Domestic Product (GDP). The debt-to-GDP ratio tends to increase annually due to the accumulation of interest payments on existing debt and the impact of nominal economic growth, which takes into account inflation.
When the average interest rate on a state's total debt exceeds its nominal growth rate, a self-sustaining cycle emerges, causing the debt to increase independently.
The national debt continues to rise as a proportion of the country's overall economic output, despite the government's efforts to maintain a balanced budget by not exceeding its revenue intake.
In the event of a reversal, the outcome is characterized as "negative," resulting in a spontaneous reduction of debt.
France is particularly vulnerable to the impact of rising interest rates due to its significant debt burden, which currently stands at approximately 119% of its Gross Domestic Product.
Professor Jagjit S. Chadha of the University of Cambridge's economics department notes that high levels of debt necessitate substantial interest payments.
A potential concern exists that if investors perceive an increased risk, it could lead to a snowball effect, resulting in higher interest rates. If interest rates rise, the burden on state resources to service the debt would likely increase.
Rising concerns over the State's ability to meet its debt obligations may lead to increased interest rates, ultimately diverting a larger portion of tax revenue away from public services and towards debt repayment.
France's debt situation may be experiencing a premature impact from the "snowball effect," a phenomenon where increasing interest payments accelerate debt accumulation.
Between 2017 and 2025, the country experienced a favorable outcome due to low interest rates, resulting in an average annual reduction of 1.74 percentage points of GDP in national debt, as indicated by Treasury data compiled in a report submitted to the National Assembly's Finance Committee in July.
France's average interest rate on its debt has experienced a modest increase, rising from 1.8% in 2023 to 2.3% by 2026, with a relatively stable growth rate of 0.5% as per the government's latest projections.
According to government projections, the national debt is expected to experience a positive growth trend in 2026, marking the first instance since 2020 in which the debt will increase without being offset by external factors, albeit at a relatively modest rate.
French Finance Minister Olivier Lescure acknowledged before a parliamentary committee that the influence of various interests is contributing to a resurgence in debt levels, however, he disputed the notion that this has created an irreversible cycle where debt continues to escalate uncontrollably.
France faces a potential economic downturn, according to projections from the French Court of Auditors and the European Commission. They anticipate that the average interest rate will surpass economic growth by the end of the decade, posing a significant challenge for the country. To mitigate this risk, France would need to not only address its substantial deficit but also achieve a primary surplus, where revenue exceeds expenditure, excluding interest payments, a goal that currently seems distant.
France is rapidly approaching a concerning fiscal situation. According to recent statements by Lescure, the country's debt burden is projected to reach approximately €91 billion annually by 2027, equivalent to approximately $102 billion, thereby surpassing the combined annual budgets for education and defense.
Several developed economies, including those with advanced financial systems, have experienced significant increases in their debt levels over the past few years.
Governments globally undertook significant borrowing at the outset of the current decade to mitigate the economic impact of the COVID-19 pandemic.
The European region experienced an increase in debt, which was compounded by the sovereign debt crisis that began in the Eurozone in 2009. At that time, significant capital injections were required to stabilize Greece, Ireland, Portugal, and Cyprus, as well as to support the Spanish banking sector.
The increasing influence of artificial intelligence companies, which are now issuing debt and competing with governments for investment, has combined with rising energy costs stemming from the ongoing conflict between the US and Israel and Iran, as well as NATO member countries' pledge to boost defense spending, to further strain public finances.
French authorities face additional challenges due to several exacerbating factors.
The nation's public debt has surpassed 119% of its gross domestic product, posing significant challenges to debt reduction efforts. Furthermore, an annual deficit of 5.1% exacerbates the difficulty in addressing this fiscal issue.
France's debt level is elevated compared to typical peacetime expectations, which would allow for lower borrowing levels, thereby enabling the government to secure financing in the event of an unforeseen issue.
France's growing elderly population is placing a significant strain on the country's finances, with a substantial increase in pension expenditures becoming a pressing concern for policymakers.
Economist Krugman notes that France is particularly noteworthy among nations facing tax issues due to its ongoing struggle to address retirement concerns in a pragmatic manner.
Prior to 2023, the age at which individuals in France could retire and receive their full pension was 62 years.
French President Emmanuel Macron successfully implemented a gradual increase to 64 in a contentious policy, despite facing significant opposition from lawmakers and protesters. However, to secure the backing of the Socialist Party in Parliament, the government was forced to temporarily delay the policy's implementation, ultimately resulting in a decline in Macron's popularity ratings.
The retirement age in many countries remains lower than that of most developed economies, with Denmark and the United States setting the bar at 67 years old.
According to Krugman, a significant number of workers in France choose to retire early in exchange for reduced pension benefits, resulting in a lower actual retirement age compared to other Western European countries.
French society and politicians are facing a long-standing challenge that spans multiple generations.
Young protesters in recent demonstrations are largely comprised of individuals who have been deprived of quality educational opportunities, while simultaneously shouldering the financial burden of supporting the retirement pensions of their older generations.
The pension system's financial burden remains a sensitive and avoided topic of discussion.
An 18-year-old student from Marseille, who participated in the protests, noted that the legitimacy of violence is a complex issue, particularly in the context of France's history, which is deeply rooted in the revolution and often requires significant action to effect change.
The notion expressed by the individual is a sentiment that is commonly held in France.
France, a nation with a rich history of social activism, has a long-standing tradition of protest as a means of safeguarding and advocating for social rights. This cultural heritage is deeply rooted in pivotal moments such as the 1789 Revolution and the influential intellectual and political movement of May 1968.
A growing sentiment among the French population suggests that their government is perceived as failing to provide its citizens with fair treatment and access to the services they are entitled to.
The government is facing mounting pressure from public demonstrations and is also being impacted by the increasing risk premium in financial markets.
Kristalina Georgieva, Managing Director of the International Monetary Fund, recently conveyed a message to the French people during an interview with CNBC, urging them to prioritize domestic economic stability.
European Commission Vice President Georgieva emphasized the importance of implementing fiscal adjustments in France, with a specific goal of reducing the country's public deficit to below 5%. She acknowledged the significant challenges faced by the French government, which operates in a parliamentary minority and is under pressure from ongoing protests, further complicated by the approaching end of its term.
The French economy is currently experiencing growth, and Europe has developed more robust mechanisms to safeguard financial stability, particularly through the European Central Bank.
The government is seeking parliamentary approval for a budget, which is typically considered viable when it receives support from at least 5% of lawmakers. However, the current proposal faces significant hurdles as it has been rejected by other major political groups.
Several economists, including Jagjit S. Chadha, believe that more substantial monetary policy adjustments are required.
Any deficit target should be set at a level below 4% to be considered convincing.
The current political environment presents significant challenges to implementing changes.
French President Emmanuel Macron is nearing the end of his second and final term in office, with the conclusion of his presidency expected in the coming months.
In April, French citizens will head to the polls to select their next president, with key political leaders opting to exclude contentious issues, such as pension reform, from their campaign promises.
Marine Le Pen, the current front-runner in the polls, has unveiled a proposed five-year fiscal discipline plan that aims to slash public spending by €140 billion, equivalent to approximately $157 billion, through reductions in the size of the French state and its contributions to the European Union budget. However, critics have expressed concerns that her plan is insufficiently ambitious and lacks clarity.
Jean-Luc Mélenchon, the candidate of the radical left, has criticized the French debt being held by the European Central Bank, a move that could set a historic precedent and have far-reaching implications for the debt credit of all eurozone countries.
The proposal has been dismissed by Christine Lagarde, the president of the bank, and the government, who characterized it as an "absolute failure.
French Minister Lescure concluded his final address to Parliament by announcing a current bond interest rate of 4.5 percent, with projections indicating a stabilization of this rate at 2.5 percent by 2027.
Noted economist Paul Krugman assesses the likelihood of France experiencing a payment suspension within the next three years as extremely low.
The current economic situation in France is cause for concern, as it appears to be perpetuating an unsustainable fiscal trajectory.
The Nobel Committee warns that a debt crisis among eurozone countries is a distinct possibility, with the potential to be more severe than the 2009 financial downturn.
Europe now possesses containment mechanisms to address economic challenges, a stark contrast to past situations. Former European Central Bank President Jean-Claude Trichet noted that the European Stability Mechanism is one such tool available for crisis management, but emphasized the importance of countries demonstrating a genuine commitment to reducing their deficits before resorting to these measures.
Several eurozone countries, including Greece, Italy, Belgium, and Spain, are at risk of being impacted by market instability due to their high debt levels, with some exceeding 100% of their GDP, a threshold that significantly increases their vulnerability to economic downturns.
Rising concerns over European sovereign debt threaten to undermine the continent's unity and potentially destabilize the region.
Countries that had to implement austerity measures to secure financial assistance from European partners during a previous crisis may question the fairness of a situation where France is exempt from similar fiscal adjustments.
The French economy, the second largest in the euro area, trails only Germany in terms of size.
Economist Paul Krugman has stated that if France required financial assistance, the cost would be substantial.
France's economic situation may have reached a critical threshold where its size and influence render it too large to be saved by external intervention.
Economist Chadha attributes the struggles of the French people to a short-sighted approach by their politicians, who prioritize maintaining public approval over implementing necessary reforms to address long-term economic challenges.
The official expressed concern that if reforms are not initiated promptly, the eurozone may be on the brink of a major crisis.
French authorities remain optimistic that a potential fiscal scenario can still be avoided. Finance Minister Moulin asserts that a 3% deficit by 2029, the government's target, is achievable if Parliament approves a budget that adheres to the 5% target for 2027. However, he acknowledges that the increasing cost of debt poses a significant challenge to this goal.
The upcoming period, spanning several months, will be crucial in determining the course of events.
The prospects for a significant impact from the "snowball" effect appear to be diminishing, contingent upon two key developments: parliamentary approval of the 2027 budget and the presentation of comprehensive financial management plans by presidential candidates participating in the April elections.
The situation may escalate if the unstable mass continues to slide down the slopes, posing a significant threat.