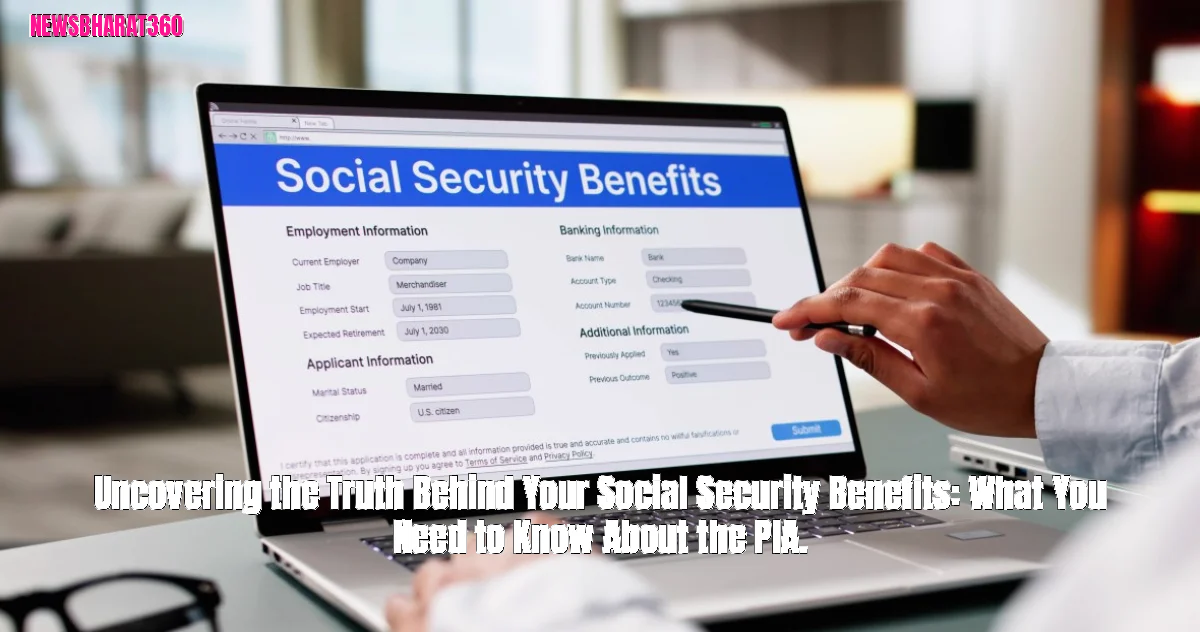

Understanding retirement planning in the United States requires informed decision-making, significantly impacting long-term financial stability. For newly arrived Latino workers, familiarity with Social Security Administration terminology is essential to accurately assess monthly benefits and the factors influencing those amounts. A crucial concept to grasp is the Primary Insurance Amount (PIA), a critical determinant of retirement benefits.
The Social Security Administration utilizes the Primary Insurance Amount (PIA) as a benchmark to determine the benefits of a worker at full retirement age. The PIA value is derived primarily from earnings recorded throughout an individual's working life and is calculated in accordance with a formula established by the agency.
To determine eligibility for benefits, the Social Security Administration first verifies that applicants meet the necessary requirements. Typically, workers must have earned 40 work credits, although individuals under a certain age may qualify for disability benefits with fewer credits, based on their age and individual circumstances.
To determine an individual's Social Security benefits, the Social Security Administration (SSA) first considers their lifetime earnings history, specifically the highest 35 years of income, which are adjusted to account for inflation and changes in national wage levels over time. This adjustment is calculated using the average indexed monthly earnings (AIME).
The agency utilizes a progressive formula that allocates varying percentages to distinct income ranges of the AIME, with inversion points dictating the applicable percentage for each segment. For the year 2027, the specified inversion points are $1,340 and $8,077 per month.
The formula includes:
Individuals can determine their Primary Insurance Amount (PIA) by combining various components before applying any necessary adjustments. As a result, two individuals with distinct work histories may receive different benefits, despite both retiring at the same age.
The timing of when an individual begins receiving retirement benefits significantly impacts the total amount of money they receive. While it is possible to apply for retirement at the age of 62, doing so prior to reaching full retirement age typically results in a reduction of monthly payments.
Individuals born between 1954 and 1960 will experience a gradual increase in their full retirement age, rising from 66 to 67 years, based on their year of birth. Those who choose to apply for benefits prior to reaching this full retirement age will have their Social Security Administration benefits reduced, with the extent of the reduction determined by the number of months they have claimed benefits prematurely.
Applicants for benefits may benefit from delaying their application, potentially resulting in a higher monthly payment. However, the decision to wait or apply immediately should be based on individual circumstances, including financial requirements, income, health, and personal objectives. To make an informed decision, it is recommended that applicants consider and compare various scenarios before submitting their application.
The online platform My Social Security enables users to access their earnings history and review projected future benefit amounts. This feature facilitates the identification of potential errors in their records and provides insight into how varying retirement ages may impact their benefit payments.
Individuals seeking clarification on the eligibility requirements, benefit calculations, and applicable adjustments for their specific situation may contact the Social Security Administration directly to address their concerns.
Additional Stories of Note